Mega Funds or Bust?
09
Episode Summary
In this episode, Earnest Sweat and Santosh Sankar explore how consensus and social validation shape venture capital, from finding anchor LPs to the growing influence of mega-funds and “kingmaker” investors. They discuss how companies staying private longer is changing fundraising, why emerging managers may need more flexible strategies, and the challenge of helping promising startups raise follow-on capital. The key takeaway: as private markets evolve, investors and founders may need to look beyond familiar playbooks, balance growth with risk, and build strategies that fit each company rather than chase consensus. Also, Caroline Hale of Citizens Private Bank shares how her venture and banking experience informs Citizens’ support for emerging managers through fundraising guidance, LP connections, and community events.
Show Notes
Topics in this conversation include:
- Defining Consensus and Finding “Anchors of Anchors” (0:06)
- Finding the First Domino and Evaluating Late-Closing LPs (3:50)
- Earnest’s Equity Research Experience With Consensus Estimates (6:22)
- Whether Non-Consensus Investments Can Survive the Wait (10:11)
- How Boutique Firms Can Find Opportunities Beyond Consensus (14:43)
- Caroline Hale’s Journey From Venture Operations to Banking (19:06)
- Citizens’ Support for Emerging Managers and GP-LP Connections (22:48)
- Whether Venture Capital and Private Equity Are Converging (30:24)
- The Funding Gap for Good Companies Approaching Series A (36:06)
- Balancing Reserves, New Investments, and Follow-On Capital (40:33)
- Alpha, Beta, and the Effects of Concentrated Capital (43:43)
- Founder Power, Secondaries, and the Risks of Consensus Funding (46:09)
- What Makes a Well-Functioning Private Capital Market? (48:44)
- AI-Era Metrics and Competing With Hyperscalers (49:17)
- Capital, Disruption, and the Episode’s Cliffhanger (51:54)
Venture has plenty of content. What it lacks is candor and curiosity about the craft. Hosted by Earnest Sweat and Santosh Sankar, Carry On is focused on what building a firm actually looks like, not the highlight reel. Each episode breaks down the X’s and O’s of venture capital, traded openly between two GPs and a small circle of friends who live this work. From first funds to franchise firms, specialists to generalists. Learn more and subscribe at www.carryonpodcast.com.
Full Episode Transcript
Santosh Sankar 00:06
What does consensus mean to you?
Earnest Sweat 00:10
I’ve been thinking about this. This might fall into consensus too, but you know, everybody’s talking about there’s like what do they say fall to brand or fall. Everybody’s moving towards comfort when it comes to, like they say, moving to consensus, but there’s other terms too like all the investors are looking to invest in the same companies. All the LPs are moving to like brand names and all of this uncertainty, and so it got me to thinking like emerging managers, and you know this is selfish for me. You know who is actually anchoring emerging managers, and so as I’ve gotten to talk to more allocators, there’s actually a level even before that. So, like, it’s gotten me to like who are the anchors of anchors, and there’s these like specific institutional family offices and fund of funds or you know endowments that carry a lot of weight that help someone become part of the zeitgeist, and so I was just curious. Like, how have you, like, if you were raising Fun One right now, like, how would you try to find those people? Because I know that they’re out there. Like, there’s like, they’re like Highlanders. It’s like you got to find, but you got to find them.
Santosh Sankar 01:44
You have to find them. Well, finding them and any LP that is actively deploying where you might be building a thesis and a strategy is, I would argue, maybe the hardest part of fundraising because when you find those, I think most quality managers know how to close them, but finding them is hard because LPs, as as a type, they don’t really want people to know. Like they have enough problems people showing up at their doorstep every day asking for money, and I think that’s partly why they also use their network as that filter, or else it becomes really hard to figure out what I spend time with and what I don’t. But there’s obviously a pitfall to that groupthink, concentration, consensus, all the stuff you just mentioned. But what I did find is I can think of a couple large endowments who do believe that the emerging sleeve is important. They do believe like this concentrated early stage exposure is important, but they also recognize that it creates a multiplicity when you need to build a portfolio, and that’s why they oftentimes show up and they either will anchor a fund to fund, or they’ll anchor the fund to fund and then do a co-investor and SMA with them in order to ratchet up the exposure alongside, because they themselves, it’s a they’re not going to be able to justify to their board and the trustees that they look and we’ve hired this person to go like steward 100 EMs or sub 100 million managers like one person’s not going to do that well like it’ll probably take at least three people but then is that the best place to kind of steward and spend time when you’re overseeing you know, $10 billion of of a UM probably not, which is why these fund of funds exist, anyways. There’s an aggregation effect.
Earnest Sweat 03:50
I think if there’s an analogy, it’s like so many talented emerging managers are setting up their dominoes, right, and they have these like it’s like a if you look from like above, it’s like a tapestry of like oh wow that’s an amazing strategy that’s congruent to all the work they’ve done in the past and how they view the world going forward. They have great references, have a ton of you know follower LP checks ready to move, or even maybe in some like people forget sometimes. There are actually large checks that are even quoted as being anchors, but wanted to come in the second close or final close. So how do you find that first domino? I think it is like I don’t know. It’s something that you have to strategize for.
Santosh Sankar 04:46
And what works for you won’t work for me. Won’t work for the next guy or gal either.
Earnest Sweat 04:51
Exactly, exactly.
Santosh Sankar 04:52
But on on on the piece of like the large LP sitting on the sideline. Waiting for that second, third, fourth close. I’ll be real here. Like those are the most annoying people in the world.
Earnest Sweat 05:06
Yeah.
Santosh Sankar 05:07
Unless they really need the time to do their work, which I’ll acknowledge some of them might, just based on when you encounter them, how long they’ve had to build a relationship, and draw lines between the data points to figure out kind of where your trajectory is and how they perceive the value of that. It’s my belief that a lot of those LPs are looking for social validation, and that cosmic social validation might be why we’re sitting in a moment where people talk about consensus capital relative to venture capital, which is a very sad place to be. And then what you’ve heard me talk about before, as to there’s now enough critical mass that it feels like there’s the concept of you buy beta and then you can buy alpha in private venture markets that didn’t exist 10 years ago, like not even close to existing 10 years ago, but it’s more kind of technical functions that allow that to happen. But like as you kind of trace it back, there’s usually some reason as to why these things sit downstream where we are, because there’s certain decisions and behaviors upstream.
Earnest Sweat 06:22
Yeah. Yeah. That social validation being closely linked to consensus is very real, and I want to pull that thread as we talk about what we’re supposed to talk about here. Before I throw out that first question, when I think of consensus, I think of people looking for safe social validation, and where it takes me my first like professional, not first professional memory, but kind of close to one, is I started out in equity research, and I’ve written about this before, but my first tie to consensus was after like updating a model using my own thoughts of like what I thought this REIT would do in different rates, how much like return they would get on the specific acquisition of a portfolio. It then would come out with our kind of NAV, and then that turned into kind of like all right, basically our EPS for the industry, which is FFO, right? And so then I would present that to one of my bosses, and he would say, “All right, go on SNL and check consensus.
Santosh Sankar 07:36
Yep.
Earnest Sweat 07:36
Does it fall in the range of what the company says? All right, that makes sense. The company should kind of know what it’s doing, but to find consensus and say, “All right, are we within a cent or two of consensus? All right, cool. Now we should feel good. It’s like, what is the point of our job if what? What if it’s not based on our assumptions? If we can back our assumptions, it’s good. But it goes back to that social validation, and I think going into our own industry, that’s where we are today. Even as direct venture investors, consensus is coming earlier and earlier.
Santosh Sankar 08:20
I parse consensus. I think social proof, social proof ultimately drives this notion of consensus. Being able to say, “Hey, look, I made a good investment, and the reason it’s good is because it got marked up X amount, or it got marked up by one of these three funds that these days we call kingmakers have marked up my investment, or look at this subject matter or this like topical area. Someone’s been king in it, and my company is great because of these three things, it is the next to be king made because that consensus thinking takes over about that particular opportunity or sector, and that fervor kind of starts to validate socially. Hey, like so and so is a good investor because they got marked up and they got in early in this kind of hot area. It’s very easy, I find, when we’re in the moment to get caught up in that. So, like you go see Splashy Series B or whatever it is, but then the one thing I always have in the back of my head is the story is not fully written till it’s written. So it doesn’t matter until those dollars create DPI, and only then do you judge whether you have portfolio envy, whether it was really a miss for you, whatever it is. But markups on the way through only have so much value. Granted, that’s how LPs might underwrite your next fund, but it’s a balance, and I think. There’s been a lot written about the value of markup, and beyond what year can you really start looking at it to kind of determine some value or read on the manager?
Earnest Sweat 10:11
Yeah, it’s the value of markup that is so true. I don’t know what my mind just went like when I got this advice once. I heard this quote from someone where they said you can’t judge someone’s parenting until they’re about 40 or 50 years in, and that’s kind of what I feel about venture capital as well. You don’t know if you’re good until the story has actually been written about your companies, and as long as companies are staying private Today, is the value of a markup that important? Is getting consensus early going to lead to more outlier outcomes or not? And I actually think that we’re going to be in a position where we have more companies. This idea of you know, when I was first getting in the industry 10 years ago, it’s like, hey, the goal is, especially Ernest, you doing, you know, I started out at Prologis. They’re like, you’re doing boring vertical SaaS where the TAM is small, all not true stuff, and they were like, you want to be non consensus and then right, but that even even underwritten in that statement was this idea that and right came in 18 months or two years or okay if it’s a long time three years, but was still able to get capital. The way the market’s moving now is, it feels like that ellipsis between non-consensus and right could be a death valley for many, and so it’s really leading people. And I’ve written about this on my Substack, but individuals having double consciousness in the earlier rounds of thinking not only what they think can be an amazing company, but what will the subsequent funders think about this company? So I say that to say I think that and right part may end up being similar to companies like an Nvidia who struggle for a very long time before it’s like, and this tailwind happens.
Santosh Sankar 12:33
I mean, let’s let’s kind of see how how it plays out because this this consensus capital thinking is is a function of frankly, there’s a lot more money that’s flooded into venture as as the asset class, and I think there’s a debate now as venture itself bifurcating to something new that the mega funds are pioneering, and what is left for everyone else. But a few weeks ago, Andreason pushed out a post that was called “Catching the Venture Bus.
Earnest Sweat 13:18
Yeah,
Santosh Sankar 13:18
and a few years prior, they wrote this piece called “The Little Tech Agenda, and a lot of people have talked about little tech, right? Gary at YC, Fred at USV, amongst others, in order to make sure we have a competitive, anti-monopolistic environment, which I think there’s there’s merit in it’s very hard to regulate that there’s very it’s very hard to kind of say this is the right answer and you keep pushing on that, but the dichotomy of little tech versus catching the venture bus, which is talking about how venture is no longer a cottage industry if you believe it is, either as an LP or GP, like you’re likely left behind, and almost read as like a it’s mega funds or bust. It’s going to kind of perpetuate. And now, like I, I totally understand. You know, we all speak our own book, myself included. But that difference is that we want to be back like the little guy, the next up and comer, be it an instinct, whatever it is. But the way to do that best is by embracing big VC, because it makes no sense that little VC, you know, necessarily has a place here. And I just don’t know how to grok that.
Earnest Sweat 14:43
I think that what we’re seeing is not only the capital flow and funds getting bigger. It’s also as a result of these companies staying private for longer and longer. So there’s more opportunities. To invest in the private rounds, and so what it’s caused is that in conjunction with the AI boom, people are moving towards momentum investing. That’s similar to public markets, and so if we take that analogy a step further, it’s like our biggest, you know, asset allocators within our asset class have become long-only hedge funds, and so how do you combat that if you’re kind of the craft boutique industry? There has to be some change there too, And so, it’s my view that using that analogy, you have to find multi-strat or different strategies that smaller boutique hedge funds have used, whether it’s been quants or those focusing on shorts, you have to be more market driven and be a market nerd as a venture capitalist more than ever. Where in the past we could just focus on the micro of like there’s this founder, this company we back great founders, people who can build markets-that’s all still true, but now to see the arbitrage windows, I think you have to have a more expansive worldview on the market and more inputs to help you find when something’s getting too exposed and and and too consensus and where there’s something a whole ton of opportunity, where you can produce alpha.
Santosh Sankar 16:48
Do you think that exists? Like at what stage? I guess do you think that that starts to become prevalent? Because there’s also a potential implication that fund sizes across the board still aren’t large enough in order to play that approach and strategy, or maybe not everyone needs to play it. There’s still ample return elsewhere by not playing that game, but playing a different game.
Earnest Sweat 17:16
I think. I think 10 years from now, if we’re having this conversation, things look a lot different, and not only what firms are doing, but what’s been what’s accepted and a term that I absolutely hate now because we use it so much legible to LPs, and so I think in different manners you’re going to start seeing smaller funds kind of just play the game that’s on the field, be market truffle pigs, and be able to utilize the relationships and expertise that they have to be able to make traditional venture bets here, make more investments in bootstrap companies that fit in verticals that they know, and lead to more kind of like, hey, we’re gonna make secondary bets based on our our underwriting of how big we think this company can get to make sure we get DPI. So I think this one size fits all. This is what we do. This is what I said I would do to LP. I think that’s going to be less and less for a lot of companies, but it’s not going to be like oh yeah we’re just going to do anything and we’re going to follow. But people are going to start having real points of views and the different types of ways they make money and add transparency to their correspondence with LPs on opportunities that they’re taking advantage of and why and what they learn from it. I think that’s the only way people are going to have to, you know, start to compete, even with regards to size.
Santosh Sankar 19:02
And now a word from our sponsor,
Earnest Sweat 19:06
Caroline. Thank you so much for being on Carry On.
Caroline Hale 19:09
Yeah, of course. I’m happy to be here with you, Ernest.
Earnest Sweat 19:12
You know, we’ve met over the years, and I’ve always been so impressed by your background. You spent a career really inside of venture as an operator, platform builder, and now as a person helping GPS on the banking side. Could you walk us through that journey and what it’s taught you, and how it’s prepared you for the role you’re in now?
Caroline Hale 19:38
Yeah, I know it’s interesting when you first start out, you don’t expect to get where you are later. So looking back is kind of fun. Yeah, I spent 10 years at three different venture funds: Sherpa Capital, Propel Venture Partners, and Resolute Ventures. Primarily focused on the operations platform and a bit on the IR side. So I really got to see what it took to build funds and firms, and it’s not easy to be an emerging manager and to get a fund started. So I saw what that was like. You know, it’s not just being the face of the brand and doing the investments. It’s the marketing, the brand development, the fundraising, the operations back office, the unsexy stuff, and then I joined First Republic in March of 2020, right as COVID was starting. So it’s a strange time to jump into banking. So I was at First Republic for three years, and now we’ve been at Citizens for three. So exactly the same team, First Republic, as we are here. So now I’ve spent six years on the banking side, focused entirely on emerging managers and LPs. So I kind of split my role today, looking at every fund that we work with and talking to them about primarily fundraising, but a lot of times, it’s other stuff too, because every fund is facing different challenges, and so I can really lean in and think back on my experience of what it was like being an operator a few years ago to what it’s like today.
Earnest Sweat 21:13
When you were making that transition from being kind of the platform op side on the GP side to now banking, did you have any assumptions of what banking bankers maybe were missing to add more value?
Caroline Hale 21:29
It’s a good question. I didn’t think about it at the time, but now sitting at a bank and having sat at two different banks, I’m definitely grateful for my experience, my 10 years on the VC side, having been there, what it’s like being inside of a fund, and a few of us on my team have all spent time on the VC side and now on the banking side. I didn’t think about it at the time, and when I joined, when Sameer Kaji hired me to join First Republic, the intention was really to focus on that gap between LP world and GP world, and trying to bridge that gap more. Where there’s always more to be done there. There still is. There’s tons of platforms out there, but you know, no, I never really thought about what it was like. But there’s certainly a differentiator. Bankers don’t always understand everything there is about venture, and venture capitalists don’t always understand what it’s like inside of a bank. That’s for sure. Yeah, we have funny conversations even today. You know, like why can’t you just make this happen? It’s like, well, financial institutions have big walls or a lot of security. There’s actually.
Earnest Sweat 22:42
There’s actually. rules here instead of just like you guys breaking rules fast.
Caroline Hale 22:47
Yes,
Earnest Sweat 22:48
That’s funny and and and kind of speaking to those gaps and and and you seeing the opportunities to fill them. Citizens runs GP’s showcases LP programming and community events that go well beyond what banks typically do. Could you tell us what the ecosystem looks like today, and why Citizens are invested in building it?
Caroline Hale 23:18
Yeah. So on our value add platform, which is built up from a couple of us on the team, myself included, were primarily focused on those you know pain points that emerging managers really face in order to stand up a fund or a firm, and so I spend most of my time on the fundraising investor relations piece, and so for me, I’m out talking LPs, almost more talking LPs than I am talking to GPs because I’m out talking to them, understanding what they’re looking for, understanding which managers are talking to, who they’re interested in, what categories are all the LPs are talking about, understanding primarily who’s interested in venture, specifically emerging managers. So most of the time, my day to day does feel like I’m actually fundraising, but I’m not raising one fund. I’m just out talking to all the LPs, and it’s nice because I’m a neutral party, so I kind of can get the real point on what LPs are thinking. The rest of the value add piece is focused on CFO operations, back office support, and then this IR fundraising piece. So it’s those extra little, you know, areas where emerging managers might struggle, spend more time, more time than they thought they were going to be spending on getting a fund started, and so yeah, Sean, Savannah, myself, we all really try to lean in, and based on the years of experience that we’ve had, either on the fun side or with the LPs today, try to alleviate some of those pain points, and yeah. Program so, GP Showcase is a webinar series that I’ve run for the last five or six years.
Earnest Sweat 25:07
Wow!
Caroline Hale 25:07
And yeah, we’ve hosted this webinar on a monthly basis, and we have five fund managers present for 10 minutes each, and we invite a large audience of LPs anonymously to listen. And basically, it’s just kind of hey, who wants to hear five interesting funds present quickly? You know, you don’t have to show up. There’s no obligation, no obligation after the event either. But it’s just an easy way to learn about what some investors are thinking. So it’s kind of fun. It’s been a cool webinar to run. I’ve heard from hundreds of fund managers that have all different flavors of investment styles, and we have an array of LPs that you know range from various geographies like Asia, Europe, U.S. primarily family offices, high net worth institutions, family offices, endowments, fund to funds, like the whole gamut. And I, anytime I meet an LP, I invite them to come join our GP showcases. There’s a really light way of joining the programming that we’re running. But outside of the GP showcases, I’d say more of our work is In person, relationships are obviously what this industry is built on, and relationships go deep. So I always tell people, just you’re always fundraising. You’re always building your network, making your relationship stronger. You never know where you’re going to meet an LP. Like it could be a friend’s house for a barbecue, a wedding, a real LP introduction. You just never know. You just have to be always open-minded. So yeah, we’re trying to think creatively, thoughtfully, strategically in how we can bring real allocators in front of general partners that are running funds. And so yeah, do you want me to give a few more examples?
Earnest Sweat 27:04
Yeah, yeah. I would love to hear more examples of how you all are. Sure. Yeah.
Caroline Hale 27:09
So some of the other in person events, most recently. So I’m sure, you know, you’ve seen a lot of spin out funds in the last year. There’s been a lot of managers that have left some of the larger groups, like Andreessen, Lightspeed, Sequoia, and so you know we’ve we’ve known each other for years, and somehow we’ll we’ll they’ll give me a call or shoot me a text that they’re finally going out on their own, and so I’ll go for walks or have coffee with those managers. But we also decided to just pull a group of them. I was actually grabbing coffee with Sarah Smith.
Earnest Sweat 27:45
Yeah,
Caroline Hale 27:46
and I was like, “Hey, do this with me. She’s like, “Absolutely, let’s grab a cool group of people. And I floated it by a few other friends, like Sam Smith, Epstein, her, and rallied. I think we had like 35 GPs come this whole season last month. I know.
Earnest Sweat 28:00
That’s so cool,
Caroline Hale 28:01
and I know it’s like who knew there were that many spin out funds, and then had a bunch of LPs come too, and really interested LPs were like, who’s raising funds? That’s fresh, so that was a cool example of a lunch that we did that was really well attended, and we had some awesome feedback on the great connectivity that’s happened already since that a month ago.
Earnest Sweat 28:24
Yeah.
Caroline Hale 28:24
Coming up, I have our annual Women Adventure Retreat, which is probably my most favorite iconic event that I get to run every year. And it’s about 100, 110 ladies, half GP, half LP. Most of the fund managers are emerging managers, and then the GPs are a mix, all U.S. based for the most part. A lot of family offices, high net worths. But then we also have a few university endowments, fund of funds, foundations. I’ve personally made sure every single LP attending is writing checks this year.
Earnest Sweat 28:56
Oh, nice!
Caroline Hale 28:57
I don’t want just the seat filled with an LP, I want them filled with an allocating LP. I want this event to be worthwhile, and it’s my sixth year, sixth or fifth, I think sixth year, running the event. We started out smaller, focused on more principal level GPs, and then decided to mix in the LPs and bring it up to the GP level, and we pick a beautiful destination in California every year. We kind of go back and forth between SoCal and NorCal, and this year is in Santa Barbara at the Ritz at the end of May. And we have a really awesome group of attendees, and we decided to add a little bit of a theme to the event this year. So underlying, like most of the events, focus on networking and bringing these people together in two days, and then there is some content, but I don’t want it to be a conference where you’re just stuck in a chair listening to a stage presentation the whole time. That’s not the point. So we have a couple awesome speakers join. Wellness is the core of the theme this year. So it’s physical wellness, mental wellness, financial wellness, and just kind of what do we all need to walk away with to be better humans? To be better, you know, better at our career, better friends, better parents. How can we be investing in ourselves? To be giving our best self to everybody else around us.
Santosh Sankar 30:24
And now back to the show. Before we kind of move on to the next thing, do you think there are two asset classes here that are actually being conflated as one?
Earnest Sweat 30:38
I think the easy answer is yes. I think the harder answer is I think all privates are mashing together.
Santosh Sankar 30:47
If we pointed, see private equity bearing down.
Earnest Sweat 30:51
If there’s an analogy, I think that it’s a nerd analogy. It’s like incursions in the Marvel Cinematic Universe. It’s like all the different universes are combining, and capitals being rained on all of it. And so you kind of have to have different strategies on what will work. I will say this conversation and the drastic change that’s needed to compete. We’re starting to see, I’m starting to see in my network individuals who are just like fed up with being a venture anymore, either straight up leaving or getting the confidence to share with their LPs. Hey, we think there’s a different strategy on what we can do. How we can combine both growth equity and the early stage and incubation.
Santosh Sankar 31:42
Yeah, I think the struggle then becomes is is that new is that new reality capable of generating the old venture returns that we had, and so maybe it’s like a nice place to gut check because we’ve there’s been an active year, obviously, in AI mainly, has had this kind of notion of consensus capital mega funds worked, and when you look at the data, right, you have you have X AI, you have Cursor, you have Open Router, you have Hugging Face. It’s kind of hard to say. At least sitting here in 2026, it’s not working. Now, it all comes down to the underlying math and and and and waterfalls. But these have directly got to a point where you’re paying down really healthy portions of these mega funds, right? Like Martina Andreessen’s been on a tear this year.
Earnest Sweat 32:41
Yeah, yes. Yeah.
Santosh Sankar 32:44
But the reason I share that is it is just a natural law of large numbers. It reduces the upside of multiples you can generate, and so how does an investor who might say, “Hey, I want 10% of my portfolio in venture, and maybe that should even be larger. What do they think about the reason that exists? And 10% of a broader portfolio can be impactful when it hits because of just a cash on cash effect. That’s just a lot harder to come by, unless you say it’s less about the multiple and just pure absolute dollar terms that one cares about, but it still needs to matter relative to a base.
Earnest Sweat 33:25
Yeah, I think in those instances, and I’m even pushing myself, kind of going back to the uniformity of investment type is not the end all be all answer, especially in a market that demands more creativity and adaptability. It’s having a sense of what type of asset you’re buying, what is the kind of the ceiling, what is the floor, and then determining what you need in ownership for it to succeed. I’m sure, and I haven’t looked at the cap tables, but I’m sure there are names in there that only got 1% point 5% and it was a healthy return for them. And so it’s about knowing, hey, this is what I think this company can do. This is what I’m willing to be included for. It’s a great logo, but I have a strategy. But it’s not every one of my deals, and I think that struggle for people is because uniformity feels good. It’s legible, it’s efficient, and that’s all like we’re getting to. It’s efficient. It’s efficient for me to say that hey, my buddy Santosh does pre-seed this check size and gets ownership for these types of exits. You should invest. Here’s his email. Like, that’s easy. It’s a lot harder to say, “Hey, my strategy is I’m gonna, I’m a fucking market hawk, and I’m going to win based on and use any types of strategy within the toolkit of private investments to win based on that asset.” It’s a lot harder, but I think that’s where the market is going. And you know, we recently had this week a dining with allocators where we had some GPs and LPs together, and there was an astute hybrid GPLP there as we were talking about like where does education go? What should children be taught around AI, and he said it should be around. You know, he brought up arts and humanities, but he said reminding humans that not everything is about efficiency, especially when you’re talking about things like beauty and truth and creative taste and creativity. Not every fucking thing is about efficiency, and so
Santosh Sankar 35:46
yeah,
Earnest Sweat 35:47
I think that’s the the piece that us as venture investors need to start to think about and push and articulate, and hopefully then those things will become legible, even if they’re in cursive to our LP base.
Santosh Sankar 36:06
Maybe kind of another way to put what you’re saying is, I think it was probably like 2021. I remember like there’s this, I forget what what triggered it exactly, but there’s almost this like moment where I looked, and I said, “Hey, we have we have an industry filter and we have a stage filter, but as cycles come and go, there are actually different stages that have a more attractive risk reward than sitting solely at the seed stage in in physical economy subject matter. Right now, you could argue the Series A-like kind of chasm is where there’s the most opportunity, and I want to kind of ask a question about that. So I’m going to put a pin in it. But at times, a few years ago, was late stage, right? And prior to that, it was pre-seed. But it does make sense. What you’re saying is, like, we’re on a private spectrum, and there’s an argument that even VCs usually take preference. There might be instances where like you might want like a fixed income strategy because for a particular company that might be better for them, and you might have an interesting risk reward relative to the capital you’ve pooled under that vehicle, however you’ve done that, but it all kind of points towards are things just going to get bigger, and who who has the right, who’s able to aggregate that type of capital and AUM that needs more discrete strategies, who is not. So there still could be kind of this event of, hey, if you’re below the size, like you just it’s hard to compete. You’re either an angel or you’re this mid-sized mega institution. That’s about it. But on my Series A point, right? We were actually speaking internally here. There’s this open question that was left on Monday. What happens to all of these like good businesses that are struggling to graduate into a Series A because they may not be able to be $10 billion companies, but they’re not necessarily mispriced either, as they currently said. There’s just a lack of interest, and like, does private equity come in? Like, what happened?
Earnest Sweat 38:25
It’s a great question, and I was actually talking to a Series A company today, and they’re on this path now of pretty good growth, have a huge king made competitor in their space in healthcare, and you know, asked me just a blunt question of like, “Hey, should we have two decks based on if we’re talking to a normal Series B venture investor and a growth equity invest? And I was like, “Absolutely, and I think it just speaks to again this this trend of like things are going to start melding together, and as an early stage venture investor, and I’m talking about pre-seed, seed, and Series A investors, you’re going to have to have an expansive Rolodex and perspective on how your portfolio companies should operate and how they should look at expand their capital, and so there’s not again going back to if if there’s anything from the SaaS industry, it just really got us comfortable with like standardization and. and routine, and nothing that has to do with any human group of humans over a number of two can you have much routine and expectations, and so the. The AI boom is forcing folks to be able to like, all right, what do we do? How should we do it? What should we change? And so I, you know, I advise them they should have two different stories and narratives around kind of like growth equity, how you get to profitability, and this will be your last check that you need before your liquidity event, and then the other is like, hey, how we’re going to the moon. But again, that also takes into account your strategy with each company. It shouldn’t be uniform.
Santosh Sankar 40:33
I still tell founders you keep one deck, but you have to qualify. Like we go through waves, right? We’re gonna go. We’ll just do a warm-up wave, and then we’ll have three waves of very intense, structured approaches. At which point, if no one bites, then you have to fall. We need to raise enough in order to go down a different path. That path may not be one where you’re not able to kind of achieve financial freedom and flexibility as a founder, but it’s going to be materially different than going to the moon, and there’s an entirely different set of players. But the big outstanding question is who is willing to honestly price a $2 billion company a day? Because like you either go seed to growth equity, you’re one round and done. What more companies probably need is like you need C, do you need A, and then from A you probably are in this bifurcated motion of do I go the B C route as traditional, or am I effectively, in some sense, in many sense, you’re recapping the business for the growth equity partner. What does that look like? And they tend to be such different stories. So, like, say, like we get to that if we need to get to it, but go try to conquer the world. It’s still, it’s still, still unseen. We actually have an LP who has been on shows with allocators who actually pushed us and said, “You have reduced how you think about reserves through this fund you’re investing in. Should you just keep it to what it is? Because if you truly believe that you have a winner on your hands, it’s non-consensus. You need it to become consensus at some point. That’s the part about being right. You might need to keep giving it some cash to sustain itself. That’s going to come out of your reserves, and we got into a bit of a debate as well, you can’t have your cake and eat it too because you need more shots on goal in this era. Yes, and in order, and you still there’s a lot of LPs who want to keep fund sizes constrained. I’ve heard of one LP that we both know that has asked for portfolios at this stage at pre-seed C to be as little as 15. It’s like that’s not enough for a GP to run a good business because then they need to be running a good business. So it’s like a bet if you can’t have your cake and eat it too, so what gives? And we’ve kind of said maybe reserves give, because you can then go raise discrete capital that might be a Series A risk or a Series B risk or a Series D risk, and the reward associated with that. So you can kind of better match risk reward when you do capital formation, but it still kind of comes back to right. There are a bunch of these great companies, or sorry, good companies that seed. They have a chance of being great, but never see that chance because there are very few firms willing to do that hard work and underwrite something that they cannot easily get marked up in under 12 months.
Earnest Sweat 43:42
That’s true, and then that makes you think of like, all right, if everybody’s going for the same things, you’ve already kind of pushed on this idea of consensus, and I don’t know if that’s the right term, but the other thing that people constantly bring up is beta. You’re buying venture beta. You’re buying venture beta. What does that mean to you when you’ve already insinuated some of the like wins that large firms who are characterized as beta have produced with open router, cursor, XAI?
Santosh Sankar 44:21
By and large, the notion of alpha versus beta is probably more of a mid stage, late stage notion, right? It needs you to think of a confluence of two, maybe three things as we talk it through. You need vast amounts of capital coming into a broader market, and you need it concentrating around something that might be a sector. That might be a particular company. It might be a set of themes, and it is doing so in a way that it can move the market or distort the market. That is happening very much. Kind of in the late stage, but it seeped into the seed stage, right? Because I think we talked about in a prior episode the barbell, where a lot of these firms are buying ownership at seed. They’re deploying scale of capital late stage, and their activity at seed is creating a similar kind of fermentation of what is consensus, or sorry, what is alpha versus beta, and while they think they might be buying alpha and buying it at high ownership, they’re accidentally many times minting beta because they’re price insensitive. And the question I have, and I’d love to hear your thoughts on this, like what is ultimately better when you are a founder, right? Is it that private market beta is good because it gives you more options? It allows you to kind of get into the zeitgeist of raising a lot of capital, or is it better to have perhaps the opposite? Because equally, when you start to aggregate capital, you can become beholden to a set of three or four funds, pretty much the same cast of characters.
Earnest Sweat 46:09
Yeah, it’s kind of like sports today, right? Where we’re kind of moving out of to buy a franchise. This is why all the sports teams are looking at private equity companies and allowing them to have more than I think right now, there’s a standard of no more than like 10, 20%
Santosh Sankar 46:25
1015, yeah, yeah,
Earnest Sweat 46:26
something like that. But when franchises cost in the multi billions, it’s not that many people who can buy that on their own. And so we’re getting to that point where yeah, if you’re a founder and you get part of the zeitgeist, you better do well because you’re only limited to those like six funds to be able to fund you. And when you start to have some, I don’t know, growth, you’re kind of screwed, and it could really hurt your possibilities of a true liquidity event. Now, what’s changed, though? The caveat I’ll say is, I would argue that founders have never had, if you’re a part of Central Casting, or have shown significant growth, founders have never had more power since I’ve been working in this industry. Not only across the table with venture capitalists, but also within their companies, and so you’re starting to see a lot more
Santosh Sankar 47:29
pendulum.
Earnest Sweat 47:30
Yeah, it’s a pendulum, but it’s also you’re starting to see just some bad things about having these, like not even benevolent dictatorships. And I was joking with someone about this earlier, do you remember like when we started in the industry, the speech somebody would give if they wanted to ask for secondaries? They’d be like, they’re like, man, I’ve been doing this for six years. My kids, I have a couple kids, and my wife or my husband is like, will you please take some off the table, so they just ask the board to show some pictures of the kid and be like, “Hey, can we get a down payment for the house? Now people are like, “I want 20% of the round, and our argument today is, “Oh, they only took 20 mil; they still have, you know, effectively 700 mil available. So we’re just in a different time. So if you’re looking at that and you’re like a hot founder, it probably makes sense for you, regardless if your company does well or not, to just like to ride with the zeitgeist. But if you’re somebody who wants to build a durable company, um, I think there are options.
Santosh Sankar 48:44
I guess the last question here on this topic: What is a good and well functioning market like private private venture private capital markets? Is it one kind of price based on fundamentals-is it something else? Because right now, I’m not sure what we have as a market. I’m not necessarily sure that it’s always pricing on fundamentals for a bunch of the things we just talked about.
Earnest Sweat 49:17
Well, I think that is the issue. We don’t have fundamentals today in a native AI world. Everything we use from rule of 40 to this should be the right churn rate, or churn rate is only for consumers. Oh shit! Now we need to do it for enterprise. I think we’re in this transitional period where we’re trying to determine what are the metrics that determine what are the rules that determine an efficient growth, hyper growth, because today all we’re relying on are top line revenue and vibes, and so that’s the situation we’re in.
Santosh Sankar 49:56
So before that. At the start of AI, we were staring down the fang. The fang, you could argue pre AI, the N wasn’t in Fang necessarily. But what I’m getting at is you’re basically competing against the hyperscalers. A lot of these tech businesses that have scaled out over the last 15 years, Meta, Apple, as a result of the iPhone, Alphabet, and its whole family, do you need mega funds to compete against what I’m going to call these collections as hyperscalers, for lack of a better word? It’s like the only way to go, kind of capture that, is to kind of compete balance sheet to balance sheet,
Earnest Sweat 50:44
yeah, our balance
Santosh Sankar 50:45
sheet being kind of mega funds.
Earnest Sweat 50:47
Yeah, I think I think in certain areas, if you’re trying to compete in edge technology, that they also have their own AI labs and infrastructure. Yes, I think this idea that you need that same type of capital push for application data layers, integration layers. I’m not so sure, and I think it’s coming down to something that you know I’ve been thinking about a lot with the king making and you know, distribution being king, and you saying like Zuck is the final boss. There’s a tension that even our industry is facing that like literally every every era faces in human modern human history, whether it’s in politics, business, whatever, art. There’s always a question: Is it like, will the mobilization of capital always win, or will it be the mobilization of people? And so that’s what we’re facing. That’s what we’re facing in our industry, and we’ll see who wins.
Santosh Sankar 51:54
I think a corollary to that, and I mentioned this to you before, a lot of a lot of disruptive technology. Oh, I’m going to say a lot. I think I could go out and say all meaningfully disruptive technology has capital associated with it. That’s the natural kind of implication of classic portfolio construction of a third, a third, a third. But this capital does it feel like capital right now in the moment we’re sitting in? Is it compressing time to scale, and/or is it compressing time to like ultimate reckoning? Like, is it actually bending physics in some sense?
Earnest Sweat 52:41
We can probably end there. I don’t know. We’ll have to come back to that one.
Santosh Sankar 52:45
If you have a thought on that, reach out to us on LinkedIn, NX.
Earnest Sweat 52:50
That’s a hell of a cliffhanger.
Subscribe
Join the Conversation
Stay close to the ideas, operators, and opportunities shaping what’s next.
Your Hosts
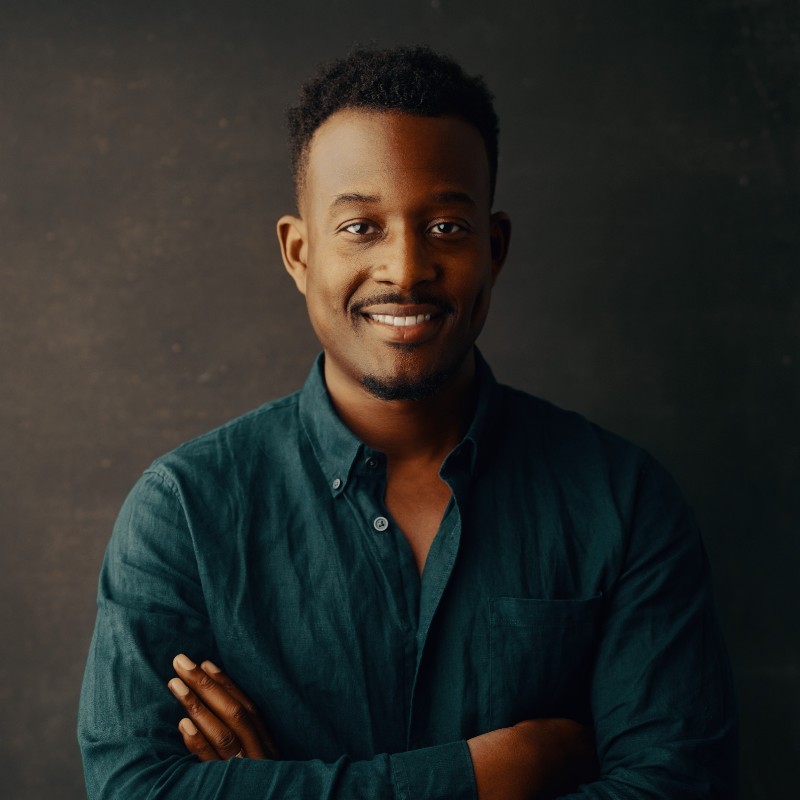
Earnest Sweat
Venture Capital Advisor & Emerging Fund Manager
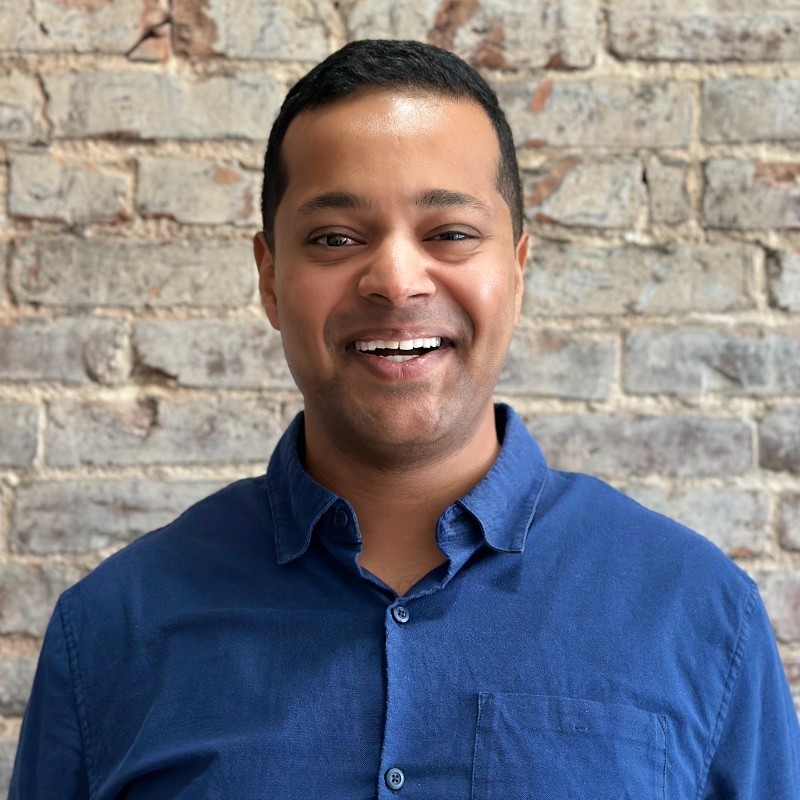
Santosh Sankar
Managing Partner, Dynamo Ventures
sponsored by